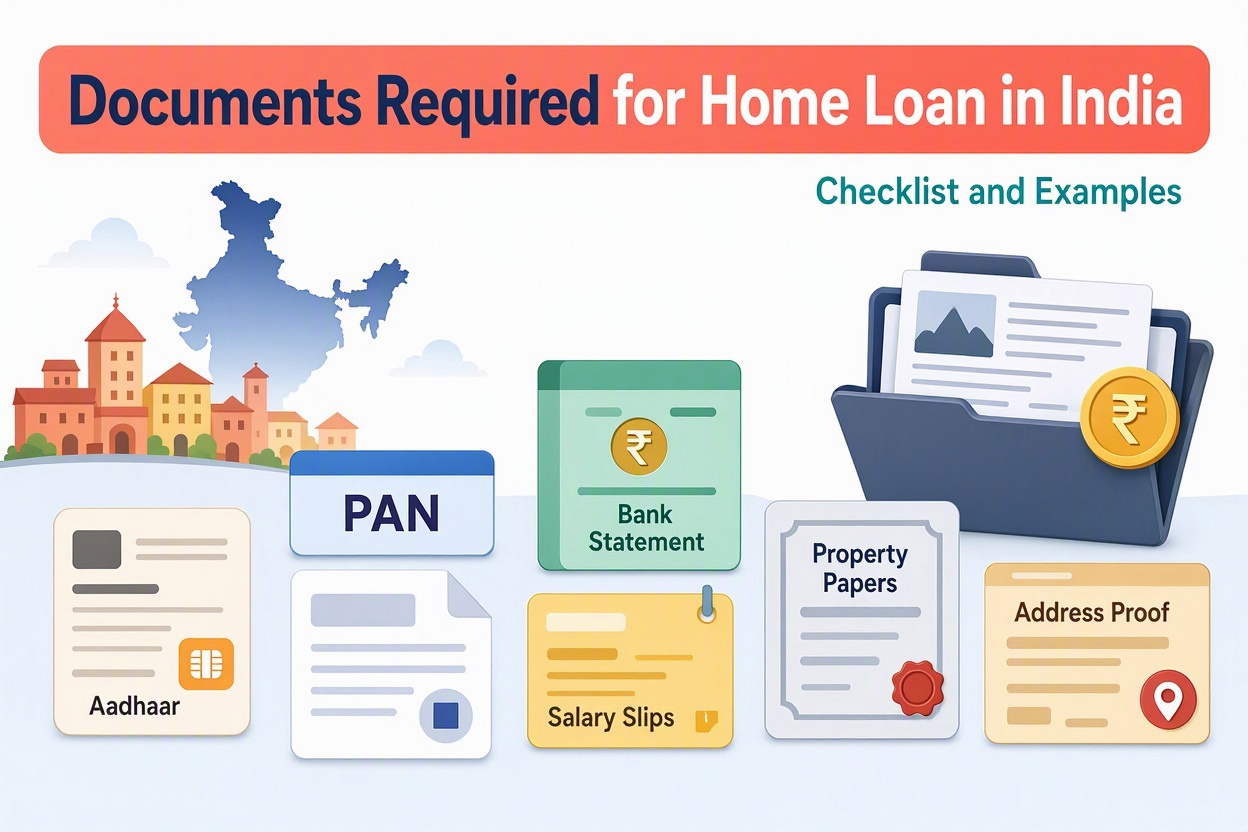
Buying a home is one of the biggest financial decisions in life. Whether you are planning to purchase a flat in Ahmedabad, buy your first home, or invest in residential property, understanding the documents required for a home loan in India can make the application process smoother and faster.
Banks and housing finance companies check your identity, income, repayment capacity, financial history, and property ownership documents before approving a home loan. Preparing the right paperwork in advance can help reduce delays and make your home-buying journey more convenient.
In this guide, City Address Realty explains the home loan documents required for salaried employees, self-employed individuals, first-time homebuyers, and property purchasers in India.
Quick Checklist: Documents Required for a Home Loan
Before applying for a housing loan, keep these commonly requested documents ready:
- PAN card or other acceptable PAN-related documentation, as required by the lender
- Aadhaar card, passport, voter ID, or another accepted identity document
- Address proof
- Recent passport-size photographs, if requested
- Latest salary slips for salaried applicants
- Form 16 or income tax returns, depending on the lender
- Bank statements, generally covering the previous 3–6 months or the period specified by the lender
- Income tax returns and financial statements for self-employed applicants
- Property documents, such as the sale agreement, title documents, or allotment letter
- Home loan application form and any additional declarations requested by the bank
Important: This is a general home loan document checklist, not a universal list. Your bank may request additional paperwork depending on your employment, income, credit profile, property type, and loan amount.
1. Identity Proof Required for a Home Loan
Identity verification is an essential part of the home loan application process. Lenders need to verify the identity of the primary applicant and, where applicable, co-applicants.
Commonly accepted identity documents include:
- PAN card
- Aadhaar card, where accepted by the lender for the relevant purpose
- Passport
- Voter ID card
- Driving licence
A PAN card is commonly requested for financial and tax-related verification. If you do not have a PAN, ask your chosen lender whether Form 60 or another permitted alternative applies to your situation.
Make sure your name and date of birth are consistent across your application and supporting documents. Differences in spelling or personal details may require additional verification.
2. Address Proof for a Home Loan
Banks generally request proof of your current residential address. Depending on their policies, acceptable documents may include:
- Aadhaar card
- Passport
- Voter ID card
- Driving licence
- Recent utility bill
- Another address document accepted by the lender
If your permanent and current addresses are different, you may need to provide additional proof.
For NRIs applying for a home loan in India, lenders may also request overseas address proof, passport details, visa or residence permit documents, and other NRI-specific paperwork.
3. Income Proof for a Home Loan
Your income documents help the lender assess whether you can comfortably repay the proposed home loan EMIs. The required paperwork differs depending on whether you are salaried or self-employed.
Documents Required for a Home Loan for Salaried Employees
If you work for a private company, public sector organisation, or government department, you will generally need the following:
- Latest 3 months’ salary slips, or the period specified by the lender
- Form 16 or income tax returns, as applicable
- Bank statements showing recent salary credits
- Employment certificate or appointment letter, if requested
- Proof of additional income, such as rental income, if applicable
- Details of existing loans and monthly financial obligations
Some banks may request six months of bank statements or additional employment records.
Tip: Ensure that your salary credits are clearly visible in your bank statements. If you recently changed jobs, keep your new appointment letter and available salary slips ready.
Documents Required for a Home Loan for Self-Employed Individuals
If you run a business, work as a freelancer, operate a consultancy, or practise as a professional, lenders may need more detailed financial records to evaluate your income stability.
Commonly requested documents include:
- Income tax returns, usually for the last 2–3 financial years, as required
- Computation of income
- Profit and loss statements
- Balance sheets, audited or certified where applicable
- Bank statements for personal and business accounts
- Business registration or proof of business existence
- GST returns, if applicable
- Professional registration or licence, where relevant
- Details of business liabilities and existing loans
The exact number of years and type of financial statements required vary between lenders.
For example, a salaried applicant may demonstrate income through salary slips and Form 16, while a business owner may need income tax returns, business financial statements, and current account records.
4. Bank Statements Required for a Home Loan
Bank statements help lenders understand your income pattern, regular expenses, existing financial commitments, and repayment behaviour.
You may be asked to provide:
- Savings account statements
- Salary account statements
- Current account statements for business owners
- Statements for other accounts relevant to your income
- Existing loan account statements, if applicable
Many lenders request statements covering the previous six months, although requirements differ.
Before submitting your statements, check that the documents cover the requested period and clearly display your name, account details, and transactions. Be prepared to explain significant unexplained deposits or irregular income, if the lender asks.
5. Property Documents Required for a Home Loan
Personal and income documents are only one part of the application. The lender also evaluates the property being purchased to establish whether it meets its legal and technical requirements.
The property documents required for a home loan depend on whether you are purchasing a new flat, a resale property, a plot, or a house under construction.
For a Ready-to-Move-In Property
Commonly requested documents may include:
- Agreement for sale or sale deed
- Title documents and ownership records
- Previous title deeds or chain of ownership documents, where required
- Approved building plan
- Building permissions, where applicable
- Occupancy certificate or completion certificate, where applicable
- Property tax receipts
- Society documents or no-objection certificate, if required
- Seller’s identity and ownership documents
- Payment receipts and details of the amount already paid
For an Under-Construction Property
The lender may ask for:
- Builder-buyer agreement or allotment letter
- Approved building plan
- Relevant development and construction approvals
- Project registration details under RERA, where applicable
- Builder’s title and project documents
- Payment schedule
- Demand letter issued by the builder
- Receipts for payments already made
For a Plot or Self-Construction Home Loan
Depending on the loan type, additional documents may include:
- Plot sale deed and title documents
- Approved layout plan
- Land-use or development permissions, where applicable
- Construction plan approved by the competent authority
- Construction cost estimate
- Contractor details, if requested
- Land records and other applicable permissions
The bank may conduct legal verification and a technical valuation before approving the property as security for the loan.
Important for Ahmedabad homebuyers: Before finalising a flat, bungalow, or plot, check the property’s ownership history, relevant approvals, and applicable RERA details. The exact documents depend on the property and transaction. Consider obtaining independent legal advice where necessary.
6. Documents Required for a Joint Home Loan
If you are applying for a home loan with your spouse, parent, or another eligible co-applicant, the lender will generally require documents from each applicant.
These may include:
- Identity and address proof
- PAN details
- Income proof
- Bank statements
- Employment or business documents, as applicable
- Photographs and application forms, if requested
The bank may consider the co-applicant’s eligible income when assessing repayment capacity. However, eligibility depends on the lender’s policies, the relationship between applicants, ownership structure, and individual financial circumstances.
If you intend to include a family member as a co-applicant, clarify the lender’s requirements before submitting your application.
7. Home Loan Documents for NRI Applicants
Non-Resident Indians purchasing residential property in India may have additional documentation requirements.
Depending on the lender and the applicant’s circumstances, these can include:
- Indian passport or other accepted identity documents
- PAN card
- Overseas address proof
- Valid visa, residence permit, or work permit, where applicable
- Employment contract or employer certificate
- Salary slips
- Overseas bank statements
- NRE or NRO account statements, as requested
- Income tax documents or other financial records
- Power of attorney documents, if applicable
Document requirements vary by lender and country of residence. Contact the bank’s NRI home loan department for a personalised checklist before applying.
8. Additional Documents Banks May Request
In certain cases, a lender may request additional records to complete its credit, legal, or financial assessment.
These may include:
- Details of existing loans and EMIs
- Loan repayment history or loan closure certificates
- Proof of additional income
- Gift deed or source-of-funds documentation, where relevant
- Business incorporation documents or partnership deeds
- Clarification of gaps in employment or income
- Documents explaining differences in names or addresses
- Additional property approvals or legal records
Submitting extra documents does not automatically guarantee loan approval. The bank will still evaluate your eligibility, repayment capacity, credit history, and the property.
9. How to Prepare Your Home Loan Documents Before Applying
A little preparation can help you avoid repeated visits, emails, and document requests.
Follow these practical steps:
Step 1: Check your credit profile. Review your credit report and look for errors or outstanding obligations that need attention.
Step 2: Organise your KYC documents. Keep your identity proof, address proof, PAN details, and other personal records ready.
Step 3: Collect your income records. Salaried applicants should organise salary slips and tax documents. Self-employed applicants should prepare tax returns and financial statements.
Step 4: Download the required bank statements. Confirm the period requested by your chosen lender.
Step 5: Verify the property paperwork. Ask the seller or builder for the documents required for the lender’s legal and technical assessment.
Step 6: Check document consistency. Review names, dates, addresses, and financial details for discrepancies.
Step 7: Ask the lender for its latest checklist. This is particularly important if you are self-employed, an NRI, or purchasing an under-construction property.
Step 8: Keep digital and physical copies. Use clear scans, label files sensibly, and submit documents through the lender’s authorised channels.
Never share original documents or sensitive financial information with unauthorised individuals.
10. Common Mistakes to Avoid When Submitting Home Loan Documents
Avoid these common mistakes to reduce unnecessary delays:
- Submitting incomplete or outdated bank statements
- Forgetting income tax returns or required salary slips
- Providing unclear scans or incomplete pages
- Using inconsistent names or addresses across documents
- Failing to disclose existing loans and financial obligations
- Overlooking property approvals and title documents
- Assuming every bank follows the same document checklist
- Making major financial commitments without understanding the lender’s requirements
A complete application makes verification easier, although the approval timeline depends on the lender, applicant profile, and property documentation.
11. Why Choose City Address Realty for Your Home Search in Ahmedabad?
Finding the right home involves more than selecting a location or comparing prices. You should also understand the property’s documentation, financing requirements, and suitability for your needs.
City Address Realty helps homebuyers explore residential property opportunities in Ahmedabad and make more informed decisions during their home-buying journey.
Whether you are looking for a first home, a family apartment, or an investment property, our team can help you navigate your property search and understand the practical considerations involved in purchasing real estate.
For property-related assistance, contact City Address Realty:
- Address: D-302, Ganesh Glory 11, Jagatpur Road, near BSNL Office, off Sarkhej–Gandhinagar Highway, Jagatpur, Ahmedabad, Gujarat – 382470
- Email: [email protected]
- Mobile: +91 7600035590
You can also explore our official website for more information about City Address Realty.
Planning to buy a home in Ahmedabad? Get your property search started with City Address Realty, and check your home loan documentation requirements with your chosen bank before finalising your purchase.
Frequently Asked Questions About Home Loan Documents
1. What documents are required for a home loan in India?
Common requirements include a completed application form, PAN details, identity and address proof, income documents, bank statements, and property papers. Additional documents depend on your employment type, lender, and property.
2. What documents are required for a home loan for salaried employees?
Salaried applicants commonly need salary slips, Form 16 or income tax returns as applicable, bank statements, identity and address proof, PAN details, and property documents.
3. What documents are required for a home loan for self-employed individuals?
Self-employed applicants may need income tax returns, computation of income, balance sheets, profit and loss statements, business bank statements, proof of business existence, and GST records where applicable.
4. Is a PAN card required for a home loan?
PAN details are commonly requested for financial verification. If you do not have a PAN, ask the lender whether Form 60 or another permitted alternative is applicable to your case.
5. How many months of bank statements are required for a home loan?
Many lenders ask for the previous six months of bank statements, but some may accept or request a different period. Check the current checklist issued by your lender.
6. Are property documents required before home loan approval?
Yes. The lender generally needs property documents to conduct legal and technical checks before final approval or disbursement, according to its process.
7. Can I apply for a home loan without Form 16?
Possibly. The acceptable alternatives depend on your employment and income profile. A lender may consider salary slips, income tax returns, employer records, or other supporting documents where permitted.
8. Can I get a home loan if I am self-employed?
Yes, self-employed applicants can apply for home loans. Approval depends on the lender’s eligibility criteria, documented income, repayment capacity, credit history, and property assessment.
9. Are the documents required for every bank the same?
No. The basic categories are similar, but individual banks and housing finance companies may request different documents and reporting periods.
10. Where can I get help finding a property in Ahmedabad?
You can contact City Address Realty at +91 7600035590 or email [email protected] for assistance with your property search in Ahmedabad.
Final Words
Preparing the documents required for a home loan in India is an important step towards buying your dream home. Start with your KYC documents, income proof, bank statements, and property paperwork, then confirm the exact checklist with your chosen lender.
If you are planning to buy a residential property in Ahmedabad, City Address Realty can help you explore suitable property options while you prepare for the financial and documentation aspects of your purchase.
City Address Realty — helping you take the next step towards finding your home in Ahmedabad.


